Vents MagaZine Music and Entertainment Magazine
Related Articles
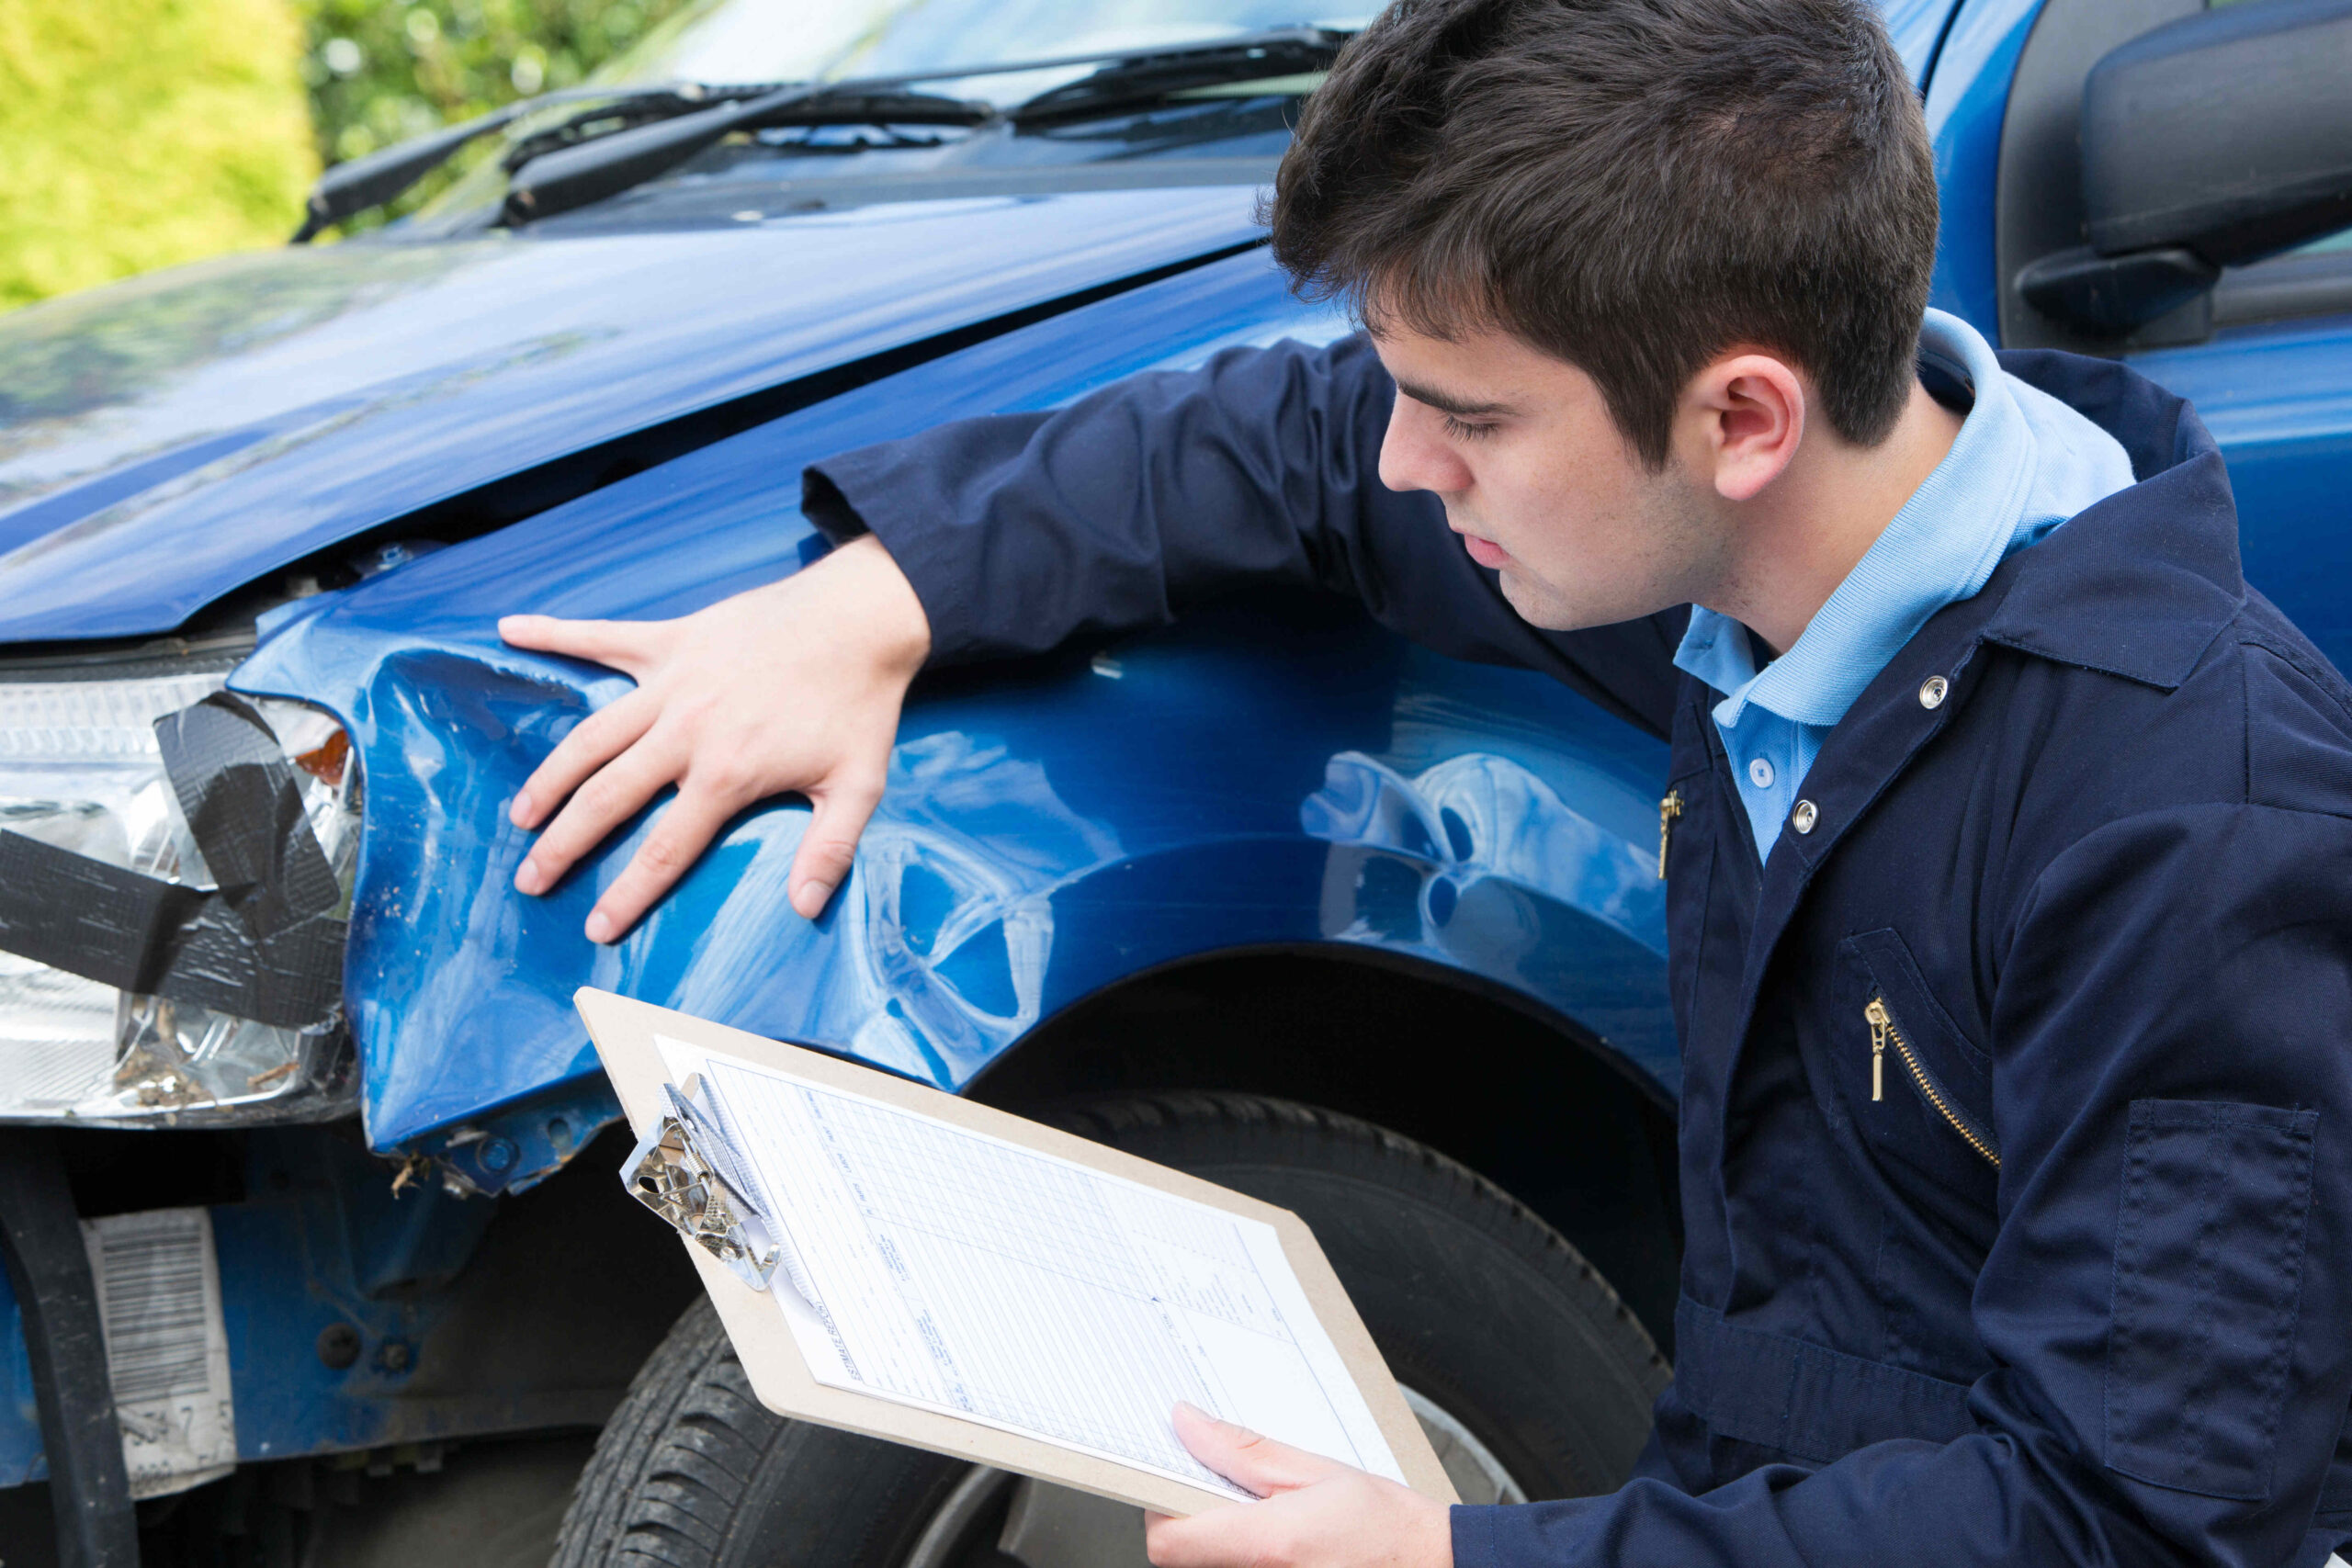
A household budget often follows a predictable rhythm: income covers monthly bills, while leftover money supports savings, debt repayment, or future plans. A car accident, medical emergency, job loss, or sudden caregiving responsibility can interrupt that rhythm within hours.
When an accident leads to medical treatment, missed work, and transportation costs, understanding available options becomes a key part of recovery. Speaking with a West Virginia Injury Law Firm may be one consideration when an injury raises questions about insurance, financial losses, or legal rights.
Meanwhile, the household must decide which obligations need immediate attention.
How Unexpected Life Events Reorder Financial Priorities
Major disruptions pull attention toward immediate stability. Someone saving for a home may suddenly need that money for medical appointments. A worker who loses a job may need to prioritize rent, utilities, groceries, and insurance while postponing major purchases. Caring for an aging parent may also require altered work hours and new household costs.
Family members may also divide caregiving, childcare, or errands differently based on circumstances. Honest conversations about income, time, and support can help anyone create a practical response in the aftermath of unexpected life events.
The Financial Impact of Accidents and Medical Emergencies
An injury can cost far more than the first medical bill. Emergency treatment may be followed by specialist visits, prescriptions, rehabilitation, and travel. If the injured person cannot work, reduced income can arrive alongside higher expenses. Some households may also need childcare or help with domestic tasks.
Even a modest emergency can strain a budget. The Federal Reserve’s 2024 household survey found that 63% of adults could cover a hypothetical $400 expense exclusively with cash, savings, or a credit card paid off at the next statement. As the report observes, “Relatively small, unexpected expenses, such as a car repair or a modest medical bill, can be a hardship for many families.”
Reassessing Goals After an Unexpected Life Change
A financial reset begins with an accurate picture of income, essential expenses, savings, insurance, and debt. Housing, food, utilities, healthcare, and transportation usually take priority. Discretionary purchases or extra debt payments may need short-term adjustments.
Consider a driver who planned to buy a home but misses several weeks of work after a collision. Redirecting savings toward treatment and basic bills may delay that goal but protect immediate stability. This guide to building a financial roadmap offers additional context on reviewing cash flow as circumstances change.
Why Emergency Savings Matter During Uncertain Times
Accessible savings can provide breathing room when income falls or expenses rise. They may reduce the need to carry credit-card balances, borrow, or sell useful belongings. Preparedness can begin with a small recurring contribution.
After using an emergency fund, a household might restore a modest monthly transfer once income steadies out once more. The aim is flexibility, not a perfect savings figure.
Making Informed Decisions After an Unexpected Injury
Good records make an accident’s financial effects easier to understand. An injured person can keep medical bills, receipts, repair estimates, insurance correspondence, and proof of missed work together. This might be done digitally, with physical documents, or through both methods.
Individuals should also review relevant insurance policies and ask qualified professionals to explain unclear legal, medical, or financial issues. Early settlement or borrowing decisions may carry lasting consequences.
Rebuilding Financial Stability One Step at a Time
Recovery rarely restores an old plan all at once. A household can first account for current income and essential bills, then address overdue expenses, rebuild accessible savings, and revisit longer-term goals. Regular budget reviews make it easier to respond as treatment ends, work resumes, or caregiving needs change. Financial priorities can change again, and that flexibility is a practical form of preparedness.
Frequently Asked Questions
How can unexpected life events affect financial priorities?
They can create new expenses, reduce income, and require households to prioritize immediate needs over savings, travel, major purchases, or other long-term goals.
Why is financial preparedness important?
Accessible savings and a flexible budget can help cover unexpected costs while limiting immediate reliance on high-interest debt or the disruption of essential payments.
How can an unexpected injury affect financial stability?
An injury may bring medical bills, missed work, rehabilitation costs, transportation expenses, and changes in household responsibilities, all of which can affect savings and debt repayment.
How should someone adjust a financial plan after a major change?
They can review income, essential expenses, insurance, savings, and outstanding obligations, then set realistic short-term priorities based on their present circumstances.