Vents MagaZine Music and Entertainment Magazine
Related Articles
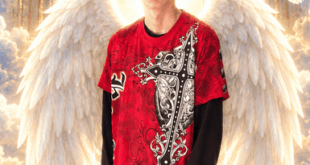
Yes, eligible members of the U.S. armed forces can obtain life insurance coverage through official military programs. For many who enlist, this protection plays a key role in safeguarding their family’s financial future.
The primary option is known as Servicemembers’ Group Life Insurance, or SGLI. It delivers low-cost term coverage to those on active duty as well as qualifying members of the National Guard and Reserve. Enrollment happens automatically for most people who meet the requirements.
Here is a clear overview of military life insurance, including how the coverage works and what options remain available after service ends.
What Is Military Life Insurance?
This type of coverage is built to deliver a financial payout if a service member dies while the policy remains in force. The benefit goes to the beneficiary or beneficiaries the member has named.
A beneficiary can be a spouse, child, parent, or any other person the policyholder selects.
SGLI functions as group term life insurance. Coverage stays in place only while the policy is active and does not accumulate cash value the way certain permanent policies do.
How Much Life Insurance Does the Military Provide?
Qualifying service members may obtain as much as $500,000 in SGLI coverage. The amount can be chosen in increments of $50,000, so members who prefer a smaller benefit can reduce the total.
Most eligible individuals are enrolled automatically at the full $500,000 level unless they actively lower or decline the coverage.
Premiums are deducted straight from military pay. The Department of Veterans Affairs lists the basic SGLI rate at 5 cents for every $1,000 of coverage. Full $500,000 protection therefore costs $25 each month, with an extra $1 for Traumatic Injury Protection (TSGLI).
These rates make SGLI a comparatively inexpensive form of military life insurance.
Who Can Get SGLI?
SGLI is open to a wide range of people serving in the U.S. military.
Eligible groups include members of the:
- Army
- Navy
- Air Force
- Marine Corps
- Space Force
- Coast Guard
- National Guard
- Ready Reserve
Certain cadets at the service academies, ROTC participants, and commissioned officers in NOAA or the U.S. Public Health Service may also qualify.
Actual eligibility depends on the individual’s duty status and training obligations.
Does Military Life Insurance Cover Family Members?
An accompanying program called Family Servicemembers’ Group Life Insurance, or FSGLI, extends protection to dependents.
Spouses who qualify may obtain up to $100,000 of coverage, provided the amount does not exceed the service member’s own SGLI benefit. Dependent children automatically receive $10,000 of coverage at no extra charge.
This option supplies military families with an added layer of financial security.
What Happens to Life Insurance After Leaving the Military?
SGLI coverage does not end the moment a person separates from service.
The Department of Veterans Affairs continues free SGLI protection for 120 days after discharge. Service members who are totally disabled may qualify for a longer free extension.
Veterans can also apply for Veterans’ Group Life Insurance, or VGLI.
VGLI lets eligible former service members keep term life insurance after they leave the military. Available amounts generally run from $10,000 to $500,000 and are tied, in part, to the SGLI level the individual carried at separation.
Is Military Life Insurance Enough?
SGLI offers solid protection, yet every household’s financial picture is unique.
A service member should weigh outstanding debts, mortgage obligations, future education costs for children, everyday living expenses, and the income the family would lose in the event of death.
For some families, SGLI might offer sufficient coverage. However, other families might choose to pair their military life insurance with a separate private policy.
Final Thoughts
Yes, the military offers life insurance called SGLI to eligible service members. The program supplies affordable coverage, automatic enrollment for many members, and supplemental options that can protect spouses and children.
Service members should periodically review both the amount of coverage they carry and the names listed as beneficiaries—especially after major life events such as marriage, divorce, the birth of a child, or transition out of the military. Keeping those details accurate helps ensure the intended recipients receive the benefits.